Fintech email marketing and lead generation work when every message does two jobs at once: it moves a qualified buyer one step forward, and it stands up to a regulator’s reading. In practice, that means pre-approved claims, clear disclosures, persona-specific messaging for CFOs, compliance officers and operations leaders, and sequences built around the buying journey (account opening, lending, or partnership). This guide covers each in turn.
Understanding the Fintech Email Marketing Landscape
Fintech buyers are cautious by training. A CFO evaluating a payments provider, or a compliance officer reviewing a vendor, is paid to find reasons to say no. Email works in this environment because it is documented, forwardable and easy to review internally, and that is also why it carries risk. Every claim you send can be screenshotted, filed and audited.
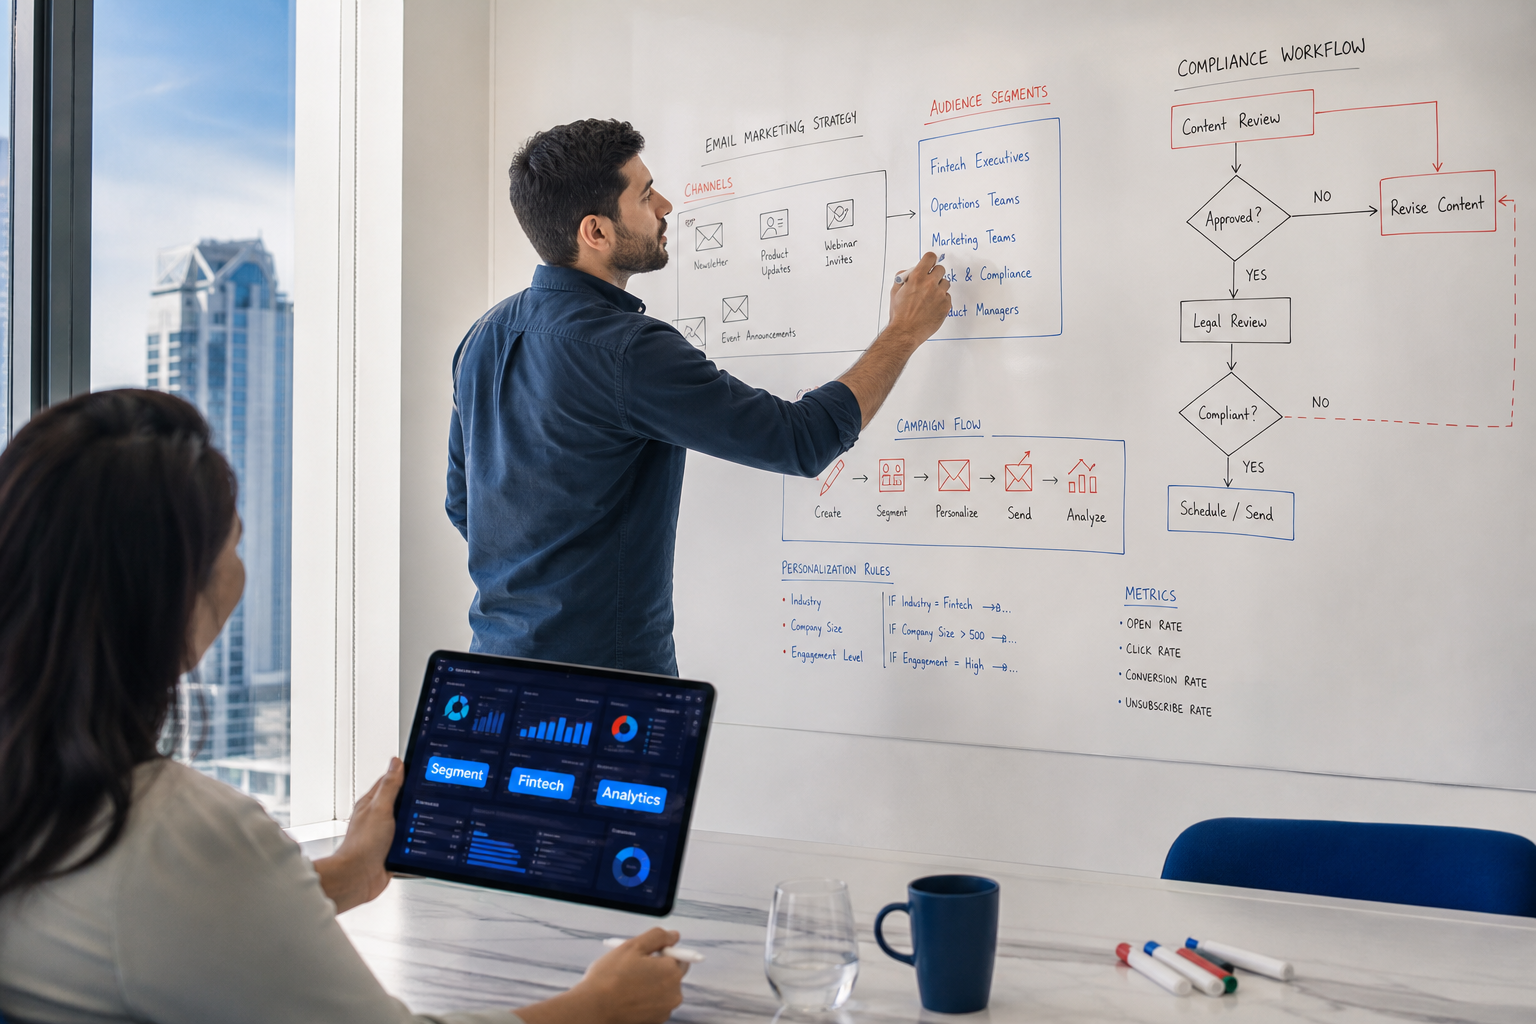
Most advice on fintech email treats compliance as a final checkbox before sending. We think that is the wrong order. We use a simple framework, CLEAR, to build compliance into the writing itself:
- Claim: Is every statement about rates, speed, savings or security substantiated?
- Limit: Are the conditions and exclusions visible near the claim, not buried?
- Evidence: Can you produce the source for any number within minutes?
- Audience: Is this the right message for this persona, jurisdiction and consent status?
- Record: Is the approved version archived, with a date and an approver?
Our own background is in live events, where a single missed detail is visible to everyone in the room. Email in a regulated sector demands the same discipline: nothing left to chance between concept and execution. It also connects the two channels. Fintech conferences and exhibitions generate many of the warmest B2B leads, and the follow-up email is where those conversations either become pipeline or fade.
Regulatory Compliance in Fintech Email: What You Must Know
What compliance disclosures must fintech companies include in marketing emails?
The exact requirements depend on your product, licence and the recipient’s location, so treat the following as a baseline and have counsel confirm it for your business.
- Sender identity and opt-out: Under CAN-SPAM in the US, emails need accurate header information, a non-deceptive subject line, a valid physical address and a working unsubscribe honoured within 10 business days.
- Consent: GDPR and the UK’s PECR require a lawful basis, and often prior consent for marketing to individuals. The UAE’s personal data protection law and local telecom rules also apply when you email recipients there.
- Licensing and partner-bank language: If a bank partner holds deposits, say so accurately. US regulators have tightened rules on how “FDIC-insured” is described, so avoid implying that the fintech itself is the insured institution.
- Credit terms: In US consumer lending, stating certain “trigger terms” such as an APR or a payment amount can require additional disclosures. Use the defined terms precisely.
- Investment and performance claims: Communications from broker-dealers and advisers must be fair, balanced and not promissory. Past-performance statements usually require specific context.
- Risk language: Where relevant, include “capital at risk” or equivalent statements in the body, not only in a linked page.
How do you balance promotional messaging with regulatory transparency?
Put the benefit and the qualifier in the same breath. A subject line like “Open an account in minutes” becomes safer and often more credible as “Open a business account in about 10 minutes (eligibility applies)”. Avoid absolute words such as “guaranteed”, “risk-free” or “instant approval” unless they are literally true for every recipient. Keep full disclosures in the email footer, but repeat any condition that materially changes the offer next to the claim itself.
Build a library of pre-approved modules (disclosure blocks, claim phrasing, footers) so marketers assemble compliant emails instead of drafting from scratch. This is the most practical form of fintech email templates for regulatory use: modular, versioned and reviewed once. A specialist partner such as Connect Digital Ventures’ fintech practice can help structure this kind of go-to-market system.
Building Buyer Personas for Fintech Email Campaigns (CFO, Compliance, Ops)
How do you target CFOs, compliance officers and operations leaders differently?
Fintech buyer persona targeting fails when one email tries to speak to everyone. The three roles worry about different failures.
| Persona | Primary concern | What to lead with | What to avoid |
|---|---|---|---|
| CFO | Cash visibility, cost of capital, risk exposure | Reconciliation time, settlement speed, a quantified business case | Feature lists and vague “transformation” language |
| Compliance officer | Audit trail, licensing, data handling | Certifications, controls, regulatory posture, a clear security document | Marketing superlatives and unsubstantiated claims |
| Operations lead | Implementation effort, exceptions, support | Integration steps, timelines, failure handling | Promises of “seamless” setup without detail |
Effective fintech CFO decision-maker messaging is short and numerate: one problem, one metric, one proof point, one low-friction next step. Compliance readers will forward your email to legal, so write for that second reader. Operations leaders respond best to specifics: what the first 30 days look like and who owns each task. In a buying committee, sequence the personas deliberately. Often the operations or finance lead raises their hand first, and compliance gets a tailored email once an evaluation begins.
Email Sequencing for Account Opening & Product Adoption
What is the ideal email cadence for account opening campaigns?
Account opening email sequences should follow the applicant’s progress, not the calendar. A sensible baseline is five to six emails across about three weeks, with triggers that pause or change the path as soon as the user acts.
- Immediately: a confirmation and the single next step (verify identity, upload documents).
- Day 2: a plain explanation of why verification is required and how long it takes, which reduces anxiety and abandonment.
- Day 5: a reminder for those who have not completed KYC, with a support option.
- Day 9: a short, practical use-case email showing what the account does after approval.
- Day 14: a final reminder with applicable terms restated.
- Post-approval: an activation series over the first 30 days (first transaction, integration, team invitations).
To avoid spam filters, authenticate with SPF, DKIM and DMARC, keep complaint rates well under 0.1%, and send transactional and promotional mail from separate streams. To avoid regulatory concerns, never present a required step as optional, and never make marketing claims inside a transactional message without checking whether that changes its legal character.
Email Strategies for B2B Fintech Partnerships & Integration

Fintech partnership outreach email is a different discipline from demand generation. The recipient is a product, partnerships or business development lead who must justify engineering time. Our guidance:
- Open with a specific shared customer problem, not your company history.
- State what each side contributes: API access, distribution, licensing, data or compliance coverage.
- Link to documentation or a sandbox so the reader can judge technical effort before replying.
- Offer a 20-minute scoping call, not a demo.
- Follow up three to four times over about five weeks, each time adding something new (a customer example, an integration diagram, a compliance summary).
B2B fintech lead nurturing for partners also benefits from in-person contact. A conversation at an industry exhibition, followed by a prompt and personal email that references what was discussed, consistently outperforms cold outreach. Treat the event as the first touch and the email as the second.
Lending & Credit Products: Email Nurture Best Practices
How should nurture sequences differ for lending products versus payment solutions?
Lending and payments differ in decision weight, time horizon and regulatory exposure, and the sequences should reflect that.
- Fintech lending email campaigns are trust-led and heavily regulated. The buyer is making a financial commitment, so sequences run six to ten weeks and focus on eligibility, process transparency and total cost. Every reference to rates, limits or approval needs its qualifying language. Avoid urgency tactics that could be read as pressure.
- Payment solutions email marketing is ROI-led and integration-led. Sequences emphasise processing costs, settlement time, supported currencies and technical fit, and often run longer in B2B because multiple stakeholders must agree.
In both cases, segment by stage (research, evaluation, application) and by behaviour. A prospect who viewed pricing and documentation needs a different email from one who only read a blog post.
Measuring Success: Metrics & KPIs Beyond Open Rates
What metrics matter most in regulated environments?
Open rates have been distorted by mail privacy features, so treat them as directional at best. Focus on outcomes tied to revenue and risk:
- Qualified reply and meeting rate for B2B outreach.
- Application start-to-completion rate for account opening and lending.
- Funded or activated accounts per email cohort.
- Pipeline velocity and time between stages.
- Spam complaint and unsubscribe rates, which signal both deliverability and message fit.
- Compliance exception rate: how many emails required rework or escalation, and how fast approvals move.
That last metric is rare and valuable. If compliance review is the bottleneck, your pre-approved modules need improvement, not your subject lines.
Related reading: Email Deliverability: What It Is and Why It Matters for Your email
Frequently asked questions
Do fintech marketing emails need a legal review every time?
Not necessarily. Review new claims, offers and templates, then reuse approved modules. Material changes to rates, terms or product claims should always be reviewed again.
How often should we email prospects in a B2B fintech sequence?
Roughly one email every four to seven days for cold outreach, and tighter, behaviour-triggered timing for applicants who are already mid-process.
Which subject lines are safest in a regulated sector?
Specific, factual lines with the qualifier included, such as "Your document checklist for account verification". Avoid guarantees, exaggerated urgency and anything that could mislead about cost or approval.
What is the biggest mistake in fintech lead generation email?
Sending one generic message to every role. CFOs, compliance and operations each need different evidence, and a single email usually persuades none of them.
Can event leads be emailed after a conference?
Yes, if you have a lawful basis or consent where required. Reference the conversation, keep the first email useful, and include a clear way to opt out.
Next Steps
Fintech email works best as a system: CLEAR-reviewed messaging, persona-specific sequences and metrics tied to revenue. If you are comparing approaches, start by auditing your current sequences against each of those three. To go deeper, explore our fintech GTM cluster for channel-specific tactics and proven frameworks, including related guides on SaaS lead generation sequences and healthcare email compliance. And if you are planning a fintech launch, exhibition or conference where email follow-up will matter, talk to our team. We would be glad to help you design the experience and the momentum that follows it.